Why your card’s annual fee keeps climbing
Why does your credit card annual fee keep rising? Learn what drives increases and how to calculate whether your card is still worth it.
Is your credit card getting expensive? Watch out for the annual fee
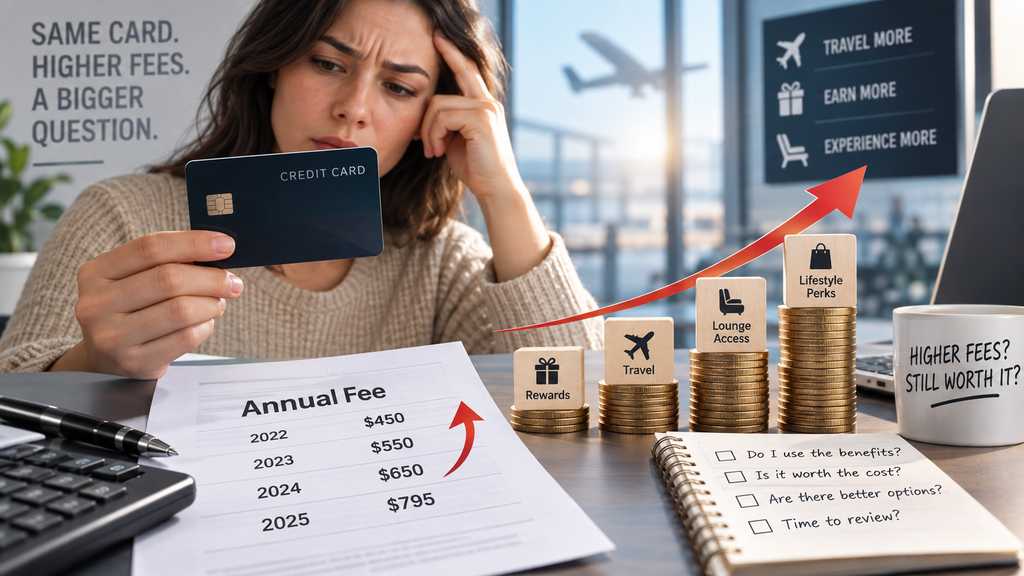
Your credit card annual fee may keep rising because card issuers are increasing the cost of premium rewards programs, adding travel and lifestyle benefits, adjusting card economics, and repositioning products for higher-spending customers.
A higher fee does not automatically mean the card is a better or worse deal.
The key question is whether the benefits you actually use exceed the new annual cost.
Why Is My Credit Card Annual Fee Increasing?
A credit card annual fee can increase when an issuer changes the card’s pricing or benefits.
Premium cards have increasingly introduced additional travel credits, lounge access, rewards and lifestyle perks while raising annual fees.
For example, recent premium-card changes have pushed some annual fees toward or above $800 per year.
The important distinction is between the value advertised by the issuer and the value you personally receive.
What Causes Credit Card Annual Fees to Go Up?
The most common factors include:
- New travel credits
- Expanded airport lounge access
- Higher rewards rates
- New hotel or dining benefits
- Additional statement credits
- Changes to the card’s rewards structure
- Higher costs associated with premium rewards programs
- Repositioning of a card toward higher-spending customers
Are Credit Card Annual Fees Rising Across the Market?
Premium cards have seen particularly significant fee increases.
The Federal Reserve Bank of New York reported that U.S. credit card balances reached $1.26 trillion in Q2 2026, showing the continued importance of credit cards in household finances.
At the premium end of the market, some cards now charge several hundred dollars per year, with certain products approaching or exceeding $800 in annual fees.
Why Are Premium Credit Cards Raising Their Annual Fees?
Premium credit cards increasingly compete by offering bundles of travel and lifestyle benefits.
A higher fee can therefore reflect a more expensive benefits package, but more benefits do not necessarily mean more value for every cardholder.
Travel Credits Can Make a High Annual Fee Look Smaller
Suppose a card charges: $795 annual fee and provides: $300 in travel credits
The simple calculation is: $795 − $300 = $495
But $300 is only worth $300 to you if you would have spent that money on eligible purchases anyway.
If you use only $150 of the credit, your effective value is closer to $150, not $300.
This is one of the most important distinctions when evaluating premium cards.
Airport Lounge Access Has Different Value for Different Travelers
Airport lounge access can be valuable for frequent travelers.
For someone who flies several times a year, lounge access may replace purchases they would otherwise make at airports.
For someone who rarely flies, however, the same benefit may have little practical value.
Don’t value a benefit according to its advertised price. Value it according to how much it saves you.
Rewards Are Valuable Only When They Match Your Spending
A higher rewards rate can help offset an annual fee when it applies to purchases you already make.
But spending more simply to earn rewards can defeat the purpose.
For example, if a card offers additional points on dining, that doesn’t make an unnecessary $500 restaurant bill a money-saving decision.
Rewards should follow your spending, not create it.
Should I Keep a Credit Card After the Annual Fee Increases?
There are several factors to consider before deciding whether to keep, change or close the account.
Compare It With a No-Annual-Fee Card
Don’t compare your card only with other premium cards.
Compare its net annual value with a card that charges $0 annual fee.
Ask Your Issuer About a Product Change
Before closing the account, ask whether the issuer allows a product change to another card.
Depending on the issuer and account, you may be able to move to a card with a lower or no annual fee.
Availability varies by issuer.
Can a Credit Card Company Raise Your Annual Fee?
Generally, federal rules permit certain annual or monthly maintenance fee increases after the first year, provided applicable requirements are followed.
Regulation Z and CFPB guidance establish notice requirements for certain changes to credit card terms.
Some changes require 45 days’ advance notice, although the exact requirements depend on the type of change.
How Much Notice Does a Credit Card Issuer Have to Give?
For changes covered by the applicable Regulation Z provisions, consumers generally receive advance notice.
The notice should explain important information such as:
- The new fee
- When the change takes effect
- The affected account terms
- Any applicable rights or options
Always read the issuer’s notice because requirements can differ depending on the specific fee and account terms.
Can You Avoid a Credit Card Annual Fee?
Sometimes. Your options may include:
- Switching to a no-annual-fee card from the same issuer;
- Asking whether a product change is available;
- Comparing the account with another card;
- Contacting the issuer about available retention offers;
- Canceling the card after considering potential credit consequences.
Does Closing a Credit Card Hurt Your Credit Score?
Closing a credit card can affect factors used in credit scoring.
One important consideration is credit utilization.
What Should You Do If You Carry a Credit Card Balance?
If you’re carrying a balance from month to month, the annual fee should not be your only concern.
The Federal Reserve Bank of New York reported $1.26 trillion in U.S. credit card balances in Q2 2026.
For a cardholder carrying revolving debt, interest costs can be much more financially significant than optimizing rewards.
Should You Spend More to Offset an Annual Fee?
No financial calculation should assume additional spending that you wouldn’t otherwise make.
If a card costs $500 per year, spending thousands of extra dollars simply to generate rewards can increase your expenses rather than reduce them.
The goal is not to earn enough rewards to justify spending more.
The goal is to maximize value from spending you already planned.
Author’s Opinion
A rising credit card annual fee deserves a fresh calculation, especially when the increase is several hundred dollars.
The key isn’t whether the issuer added more benefits. The key is whether those benefits match the way you actually spend, travel and use your card.
If you already use the credits and rewards, the additional fee may be offset by benefits you would have purchased anyway.
If you don’t use them, the advertised value can be misleading for your personal budget.
The simplest test is: what did I actually save during the last 12 months, and how much did I pay for the card?
That answer gives you a much clearer picture than the marketing value attached to every perk.
And if you carry a balance, remember that rewards optimization comes after understanding your interest costs.
Recommended Content
Health insurance
Health insurance options may change. Learn why premiums could rise, insurers may exit markets and how to prepare.
Continue reading * You will remain on the current website